
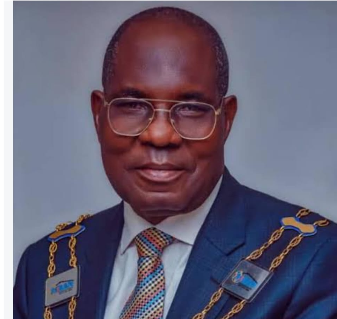
By Johnbosco Agbakwuru
ABUJA–Nigeria can deliver at least 500,000 housing units annually only if it restructures housing finance around long-term capital, transparent land records and reliable market data, immediate past President of the Mortgage Banking Association of Nigeria (MBAN), Mr. Ebilate Mac-Yoroki, has said.
Mac-Yoroki, Chairman of CityCode Mortgage Bank Limited, made the proposals in a position paper presented at the MBAN Annual Conference and Gala Dinner in Abuja, titled “Scaling Nigeria Housing Supply to 500,000 Units Per Annum: A Market-Driven Policy Framework for Nigeria.”
He said Nigeria’s housing deficit, estimated at over 17 million units, cannot be closed through government budgetary allocations and short-term commercial bank lending alone. Formal housing delivery has historically remained below 50,000 units yearly, requiring a tenfold expansion to meet the proposed annual target.
“Achieving a target of 500,000 housing units per annum requires solving the primary systemic failures in Nigerian real estate: capital mismatch and information asymmetry,” Mac-Yoroki said.
He described the mismatch between short-term bank deposits and long-term mortgages as a central obstacle to affordable homeownership. Commercial banks typically mobilise deposits with maturities of 30 to 90 days, while mortgages often run for 15 to 25 years.
“Targeting 500,000 units requires institutional patient capital to bridge this duration gap,” he stated.
Mac-Yoroki proposed channelling long-term funds from Pension Fund Administrators (PFAs), insurance companies and foreign portfolio investors into housing finance. Primary mortgage banks and the Nigeria Mortgage Refinance Company (NMRC), he said, should serve as channels for converting such investments into sustainable mortgage lending.
He called for the expansion of Mortgage-Backed Securities (MBS), covered bonds, Residential Real Estate Investment Trusts (REITs) and specialised housing debt funds.
Mortgage securitisation, he explained, would allow financial institutions to pool mortgage loans, sell them to institutional investors through the Nigerian Exchange (NGX), and recycle the proceeds into new lending.
He also proposed residential REITs and forward-purchase investment funds, under which investors would commit to buying homes before construction. According to him, this would give developers guaranteed buyers and reduce the financial risk of large-scale housing projects.
Mac-Yoroki further recommended blended financing through green bonds, social housing bonds and government-backed infrastructure bonds, supported by federal credit guarantees. He said subsidies and shared-equity schemes could make long-term mortgages more affordable for low- and middle-income Nigerians.
A major element of the proposal is the establishment of a Central Housing Depository (CHD), modelled on the clearing and settlement infrastructure of the capital market. It would provide a unified digital platform for property ownership records, mortgage registration, title transfers and verification of existing claims.
Mac-Yoroki said more than 90 per cent of land in Nigeria remains unregistered, contributing to ownership disputes, multiple-sale fraud, prolonged mortgage processing and weak collateral value.
The proposed depository would connect state Geographic Information Systems (GIS) and land registries, enabling investors, lenders and regulators to verify ownership and existing mortgages or liens. He said it could reduce title perfection from months to days and improve confidence in real estate investment.
“Deepening capital markets creates the funding capacity, while a Central Housing Depository and standardized housing data provide the transparency, velocity, and trust required to attract institutional capital at scale,” he said.
Mac-Yoroki also called for a national housing information system to address the shortage of credible market data. He proposed that the MBAN Secretariat become the principal clearinghouse for housing finance information, tracking mortgage originations, disbursements and loan performance across commercial mortgage banks, government programmes and institutional lending platforms.
He recommended the creation of an Inter-Agency Housing Data Directorate within the Federal Ministry of Housing and Urban Development to work with MBAN on policies, land reforms and budgetary decisions.
Improved data, he said, would support automated credit assessment, extend mortgage opportunities to informal-sector workers and enable the use of Automated Valuation Models (AVMs) to standardise property valuation and shorten approval periods.
On housing supply, Mac-Yoroki identified land tenure complications, rising construction costs, inadequate infrastructure and cumbersome regulatory approvals as major barriers. He called for harmonisation of Governor’s Consent procedures under the Land Use Act, wider adoption of digital land administration and single-window platforms for planning and construction permits.
He also advocated increased domestic production of cement, steel and alternative building materials to reduce exposure to foreign exchange fluctuations and imported inputs. Infrastructure such as roads, electricity and water supply, he noted, can account for 20 to 30 per cent of housing development costs, hence the need for public-private partnerships.
Mac-Yoroki outlined a three-phase, 36-month implementation plan. The first 12 months would focus on developing a regulatory framework for the Central Housing Depository with the Securities and Exchange Commission (SEC), Central Bank of Nigeria (CBN) and Federal Ministry of Housing and Urban Development.
Between months 12 and 24, the plan proposes issuing residential mortgage-backed securities under NMRC-supported refinancing arrangements and integrating state GIS databases into the depository. The final 12 months would deploy forward-purchase REIT investments for large-scale residential construction and introduce national automated property valuation systems.
“Targeting 500,000 housing units per year requires moving beyond traditional budgetary allocations toward market-driven infrastructure,” Mac-Yoroki said.
Naira weakens 0.22% as FX turnover slows to $1.45 billion in November’s first week
The naira recorded a marginal 0.22% depreciation in the first week of November, closing at N1,349 per dollar on November 6, as reported foreign exchange turnover on the Nigerian Foreign Exchange Market (NFEM) remained su...

No comments yet. Start the conversation.